South Florida Pre-Construction Quarterly: The Q3 2026 Report
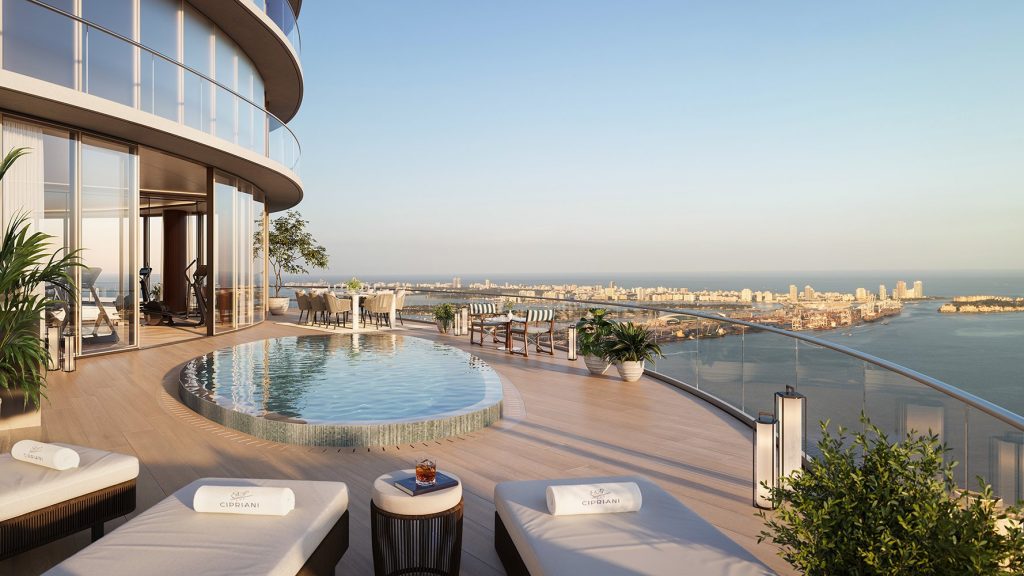
As of September 2026, South Florida’s luxury condo market is running two speeds: Miami-Dade $1M+ sales rose 15.5% year-over-year in July while overall condo supply sits at 12 months, a buyer’s market. New-development contracts at towers like Cipriani Residences Miami (80%+ sold) keep absorbing, and developers are cutting deposits to roughly 30% to keep pace.
One housekeeping note before the numbers: Q3 2026 is not over. This report covers the quarter to date — July 1 through mid-September — using the most recent verified data available: July 2026 county closings from the MIAMI Association of Realtors (released August 17, 2026), Q2 2026 new-development pricing, and project-level sales milestones announced in July and August. August county figures had not been published when this went to press. Where the picture is provisional, we say so.
The headline is divergence. The resale condo market — especially older buildings absorbing Florida’s post-2022 structural-reserve rules — remains a deep buyer’s market. The luxury and new-development segment is behaving like a different asset class entirely, with $1M+ sales up double digits in all three counties. For buyers tracking projects through our New Developments hub, that split is the single most important context for every pricing conversation this fall.
What has sold in Q3 2026 so far, and at what price per square foot?
The freshest county-level closings data covers July, the quarter’s first month. According to the MIAMI Association of Realtors’ August 17 release, Miami-Dade closed 1,026 existing condo sales in July 2026, up 11.4% year-over-year, with a median existing-condo price of $400,000 (down 1.5% from $406,000). The luxury tier did the heavy lifting: total $1M+ sales rose 15.5% year-over-year to 394 transactions. Cash covered 47.5% of all Miami existing condo sales.
On price per square foot, the best current luxury benchmark comes from CondoBlackBook’s Q1 2026 summary — the last full-quarter luxury dataset published: a median of $1,040 per square foot for Miami $1M+ condo resales (down 3.7% year-over-year), with Brickell at a record $950 per square foot and Miami Beach at $1,178. New-development asking prices run well above resale: Q2 2026 reference bands compiled by Manhattan Miami put Brickell new product at $1,200–$1,500+ per square foot, Edgewater at $800–$1,100+, and Miami Beach at $1,100–$1,600+, with branded oceanfront trading above the band. At the extreme, The Residences at Mandarin Oriental on Brickell Key has asked approximately $6,300 per square foot for its $49.9 million penthouses — a mainland Miami record.
Project-level velocity in Q3 to date has been genuinely strong at the top:
- Cipriani Residences Miami (Brickell, Mast Capital) topped off at roughly 950 feet in July 2026 and reported surpassing 80% sold ahead of a summer 2027 delivery, per PROFILEmiami’s July 23 sales update.
- 2200 Brickell received its Temporary Certificate of Occupancy in August 2026 at 85% sold, releasing its final residences as move-ins began.
- The William Residences (North Miami Beach) reported 35% sold since its late-2025 launch — a reminder that velocity varies sharply by submarket and price point.
Which submarkets led Q3 — Brickell, Edgewater, Miami Beach, Fort Lauderdale, or West Palm Beach?
By growth rate, West Palm Beach and greater Palm Beach County led the quarter to date. July condo sales jumped 18.6% year-over-year to 914 closings at a median of $312,500 (up 4.0%), and $1M+ sales countywide surged 36.5% to 445 transactions, per the MIAMI Association of Realtors. Condo supply sat at just 6.7 months — the only balanced condo market among the three counties — and 57.2% of condo purchases were cash. On the new-development side, David Siddons Group’s 2026 West Palm Beach analysis pegs new luxury product at $2,000–$3,000 per square foot for entry luxury and $3,000–$5,000+ at the trophy tier (South Flagler House). Our Olara West Palm Beach buyer’s guideand Mr. C Residences guide track the two most active mid-tier launches; Olara was roughly 50% presold as of late 2025 with construction past the 15th of 26 floors.
Brickell led on absolute absorption. Between Cipriani’s 80%+ and 2200 Brickell’s 85%, the submarket’s late-cycle towers are clearing, and the Mandarin Oriental penthouse pricing reset the mainland ceiling. Edgewater remains the volume story — The Cove Residences launched from the $900,000s and broke ground in March, and Villa Miami continues selling; see our Edgewater new-developments market guide for the full roster.
Miami Beach is the priciest and choppiest: luxury resale PPSF fell 14.8% year-over-year in Q1 2026 to $1,178 even as new oceanfront product (The Perigon, 7200 Collins — 93% pre-sold at groundbreaking) commands far more. Fort Lauderdale sits in between: Broward’s existing condo market is soft — July sales down 2.8%, median down 3.8% to $255,000 — but the county’s $1M+ segment rose 33.9% year-over-year, and branded waterfront projects covered in our Fort Lauderdale 2026 guide — led by The St. Regis Resort Residences Bahia Mar — sell to a different buyer than the county median suggests.
The submarket matrix: PPSF, direction, and velocity
South Florida condo submarket matrix — Q3 2026 to date (compiled September 2026 from sources dated as noted)
| Submarket | Benchmark PPSF / median | YoY direction | Inventory / velocity note | As of + source |
| Brickell (luxury resale) | $950/SF (record); new dev $1,200–$1,500+/SF | Up (resale record) | Cipriani 80%+ sold; 2200 Brickell 85% at TCO | Q1 2026 CondoBlackBook; Q2 2026 Manhattan Miami; Jul–Aug 2026 PROFILEmiami |
| Edgewater (new dev) | $800–$1,100+/SF asking | Flat-to-up | Cove Residences launched from $900Ks, broke ground March 2026 | Q2 2026 Manhattan Miami; Mar 2026 CondoBlackBook |
| Miami Beach (luxury resale) | $1,178/SF; new dev $1,100–$1,600+/SF | Down 14.8% (resale PPSF) | 99 days on market; 7200 Collins 93% pre-sold | Q1 2026 CondoBlackBook; Mar 2026 CondoBlackBook |
| Fort Lauderdale / Broward (all condos) | $255,000 median | Down 3.8% | 10 months supply; $1M+ sales +33.9% YoY | Jul 2026, MIAMI Assoc. of Realtors |
| West Palm Beach / Palm Beach Co. (all condos) | $312,500 median; new dev $2,000–$5,000+/SF | Up 4.0% | 6.7 months supply; $1M+ sales +36.5% YoY | Jul 2026, MIAMI Assoc. of Realtors; Mar 2026 David Siddons Group |
| Miami-Dade countywide (all condos) | $400,000 median; $1,040/SF luxury median | Down 1.5% (median) | 12 months supply; $1M+ sales +15.5% YoY | Jul 2026, MIAMI Assoc. of Realtors; Q1 2026 CondoBlackBook |
Stated in prose for the record: as of the July 2026 releases, Miami-Dade condos carry 12 months of supply at a $400,000 median; Broward carries 10 months at $255,000; Palm Beach County carries 6.7 months at $312,500. Luxury resale PPSF medians run roughly $950 in Brickell, $1,178 in Miami Beach, and $1,040 across Miami’s $1M+ market, while new-development asking prices range from roughly $800 per square foot in Edgewater to $5,000+ at West Palm Beach’s trophy tier.
Is South Florida’s condo market oversupplied going into Q4 2026?
Yes and no — and the distinction is the whole game. Statewide, Florida active condo listings have more than doubled since 2023 to roughly 68,757 units, and the median South Florida condo sale price slipped 1.5% year-over-year to $310,000, per Commercial Observer’s June 2026 analysis. That glut is concentrated in older buildings — stock 30+ years old absorbing mandatory structural inspections and reserve funding under Florida’s post-Surfside law. Condo analyst Ana Bozovic calls it a “double whammy” of rising carrying costs and buyer caution.
The tiers tell a different story. Miami-Dade’s overall 12 months of condo supply was actually down 11.8% year-over-year in July — inventory has now declined for six consecutive months. Miami’s $1M+ luxury segment carried 19 months of supply in Q1 2026, elevated but improving 15.8% year-over-year. And the newest product barely touches the resale market at all: Q2 2026 luxury pre-construction contracts cleared 12–18% above initial release pricing per Manhattan Miami’s market analysis, while the Standard Residences Midtown sold 70% within three months of its 2026 completion window. High-end demand has a demographic floor: Miami’s millionaire population grew 94% from 2014 to 2024, West Palm Beach’s grew 112%, and Q1 2026 transactions above $10 million doubled year-over-year.
The honest read for a pre-construction buyer as of September 2026: oversupply is real in the sub-$1M resale tier and gives you leverage on any developer competing with nearby resale product. It is largely absent at the branded-waterfront tier. Our September 2026 PPSF index tracks the new-development side of that ledger monthly.
What deposits and incentives are developers offering in Q3 2026?
Deposit structures have loosened meaningfully from the 2021–2023 cycle. Miami condo analyst Peter Zalewski documented developers cutting required deposits from 50% of purchase price to roughly 30% — about $200,000 less cash per $1 million — while raising broker commissions from 5% to as much as 7% to keep sales galleries busy. The standard Florida schedule now clusters around 10% at contract, 10% at groundbreaking, and 10% at top-off, with the balance at closing; ultra-luxury projects still ask 40–50% across four or five milestones.
Beyond deposits, incentives verified in 2026 marketing and coverage include mortgage rate buydowns of one to three years, closing-cost credits through preferred lenders, and 2–5% discounts for all-cash purchases, per Manhattan Miami’s 2026 pre-construction guide. At the trophy tier the incentives get baroque: Mandarin Oriental buyers received complimentary Harrods Interior Design consultations, and Pagani Residences’ first penthouse buyers were offered a “Miami” edition Pagani Utopia Roadster. Zalewski expects free maintenance-fee periods, unit upgrades, and extra parking to follow if the market softens further. If you are weighing an exit before completion instead, read our guide to assignment rights and exit options in Florida contracts.
What delivers in Q4 2026 — and what should buyers watch next?
The delivery pipeline is the quarter’s quiet story. 2200 Brickell began welcoming residents in August; Arbor Coconut Grove closed out its spring TCO cycle; The Perigon is topped off on Mid-Beach. Our near-completion 2026 deliveries tracker follows every South Florida luxury project with a certificate of occupancy in sight, and the 2027 Delivery Calendar (September update) maps the far larger wave behind it — including Waldorf Astoria Miami, whose ninth and final cube began rising this month as Florida’s first supertall nears topping out.
Three things to watch between now and the Q4 report. First, the August and September county releases: if $1M+ sales hold double-digit growth through quarter-end, the luxury divergence is a trend, not a summer anomaly. Second, deposit terms — a second broad cut below 30% would signal developers see softness ahead. Third, Q4 launch pricing in West Palm Beach, where the county’s 6.7-month supply gives developers more pricing power than anywhere else in the region. For monthly granularity between quarterlies, follow the South Florida Pre-Construction Monthly.
Frequently Asked Questions
How is the Miami luxury condo market performing in 2026?
Strongly at the top, softly below. Miami-Dade $1M+ home and condo sales rose 15.5% year-over-year in July 2026 to 394 transactions, and beachfront $5M+ condo sales were up nearly 30% in Q2. Meanwhile the overall condo median slipped 1.5% to $400,000 with 12 months of supply — a buyer’s market concentrated in older buildings, as of September 2026.
What is the average price per square foot for Miami condos in 2026?
Miami’s $1M+ luxury condo resales carried a median of about $1,040 per square foot in Q1 2026, per CondoBlackBook — roughly $950 in Brickell and $1,178 in Miami Beach. New pre-construction product asks more: about $800–$1,100 per square foot in Edgewater, $1,200–$1,500+ in Brickell, and $1,100–$1,600+ in Miami Beach as of mid-2026.
Is Miami’s condo market oversupplied in 2026?
The resale market is: Florida active condo listings roughly doubled since 2023 to about 68,757 units, and Miami-Dade carries 12 months of condo supply as of July 2026. But inventory has fallen for six straight months, and the oversupply concentrates in buildings 30+ years old facing new reserve and inspection costs — not in new luxury developments, which kept absorbing through Q3.
Which South Florida submarket is strongest for pre-construction in 2026?
West Palm Beach, by the numbers. Palm Beach County condo sales rose 18.6% year-over-year in July 2026, $1M+ sales jumped 36.5%, and condo supply sits at just 6.7 months — the region’s only balanced market. New trophy product there asks $3,000–$5,000+ per square foot. Brickell leads on absolute absorption, with major towers 80–85% sold.
What deposits do Miami pre-construction condos require in 2026?
The common 2026 structure is roughly 30% before closing — typically 10% at contract, 10% at groundbreaking, and 10% at top-off — down from the 50% many developers required earlier in the cycle. Ultra-luxury projects still ask 40–50% across four or five milestones. Florida law requires the first 10% to be held in escrow until closing.
What incentives are Miami condo developers offering in 2026?
Verified 2026 incentives include reduced deposits (from 50% toward 30%), mortgage rate buydowns of one to three years, closing-cost credits through preferred lenders, and 2–5% discounts for all-cash buyers. Broker commissions have risen to as much as 7%. Trophy projects add bespoke perks — design consultations at Mandarin Oriental, a limited-edition hypercar for Pagani Residences penthouse buyers.
Are Miami condo prices going up or down in 2026?
Both, by tier. The Miami-Dade existing-condo median fell 1.5% year-over-year to $400,000 in July 2026, and Miami Beach luxury resale PPSF dropped 14.8% in Q1. But Brickell luxury resales hit a record $950 per square foot, beachfront average condo prices rose 6%, and Q2 2026 pre-construction contracts cleared 12–18% above initial release pricing.
How much of the Miami condo market is cash?
Cash covered 47.5% of Miami-Dade existing condo sales in July 2026, per the MIAMI Association of Realtors — versus 35.1% of all closed sales. Palm Beach County ran higher still at 57.2% of condo purchases. Pre-construction deposits are effectively always cash, since mortgage financing only enters at closing.
What new condo buildings deliver in South Florida in late 2026?
2200 Brickell received its TCO in August 2026 and began move-ins at 85% sold; Arbor Coconut Grove and the Standard Residences Midtown delivered earlier in the year. The Perigon on Mid-Beach is topped off. The much larger delivery wave lands in 2027, led by Waldorf Astoria Miami, Florida’s first supertall, and Cipriani Residences Miami.