Buying a South Florida condo while you keep your New York apartment
A South Florida condo and a New York apartment can both be real homes. Florida homestead, New York domicile and New York’s 184-day residency test are not the same question, and the difference can cost real money.
Florida homestead, New York domicile and New York statutory residency are three different tests. Keeping a New York apartment can still be a permanent place of abode under New York Tax Department guidance.
A South Florida condo and a New York apartment can both be real homes. Florida homestead, New York domicile and New York’s 184-day residency test are not the same question. This guide is for snowbirds buying a new-development condo in South Florida while they keep the apartment. It is not legal or tax advice.
The doorman in New York still has your name. The new tower you picked from Miami’s new developments has a key fob and a closing date that may be two or three winters away. You can own both. The harder question is which one Florida will treat as a permanent residence, and which one New York will still treat as your life.
They do not use the same test, and a buyer who collapses them into a single “I moved” story is asking for trouble.
If you are choosing a building, start with The New York to Miami relocation guide. This story is for the snowbird who keeps the New York apartment. A Florida attorney and a tax adviser who know both states should apply these tests to your facts before you sign or file anything.
Three tests that can cost you real money
This is not a determination of your residency.
| Question | Official test, as written |
|---|---|
| Florida homestead | You own the property and make it your permanent residence, or that of a dependent, by January 1, and you file Form DR-501 with the county property appraiser by March 1 of the tax year. The property appraiser decides whether the exemption applies. |
| Florida declaration of domicile | A person who has established a Florida domicile but who maintains another place of abode in another state may file a sworn statement with the clerk of the circuit court that the Florida place of abode is the predominant and principal home. The filing is one way to manifest and evidence domicile; it does not repeal other methods of proving it. |
| New York domicile | You can have only one domicile. A New York domicile does not change until you demonstrate, with clear and convincing evidence, that you have abandoned it and established a new domicile outside New York. It is not enough simply to file a certificate of domicile or register to vote in the new location. All aspects of a person’s life are considered. |
| New York statutory residency | You may be a New York State resident even if your domicile is not New York, if you maintain a permanent place of abode in the state for substantially all of the taxable year and you spend 184 days or more in New York State during the taxable year. Any part of a day is a day, and you do not need to be present at the abode for the day to count. New York City uses the same structure inside the city. |
Florida homestead is not a New York off switch
Florida homestead is a property-tax exemption, not an income-tax off switch for New York. The Florida Department of Revenue’s PT-113 brochure says that when someone owns property and makes it his or her permanent residence, or the permanent residence of a dependent, the property may be eligible. Eligibility for a given tax year depends on making it your permanent residence by January 1 and filing DR-501 by March 1.
Those two dates are the ones that matter to your money. If the condo is still a hole in the ground in January, it is not yet the January 1 residence that a tax year’s exemption requires. Time the filing to the year you will actually own and occupy the unit.
For a first-time filing, the brochure asks whether you claim residency in another county or state. It lists items a property appraiser may ask for to prove residency, including a Florida driver license or identification card number, evidence of giving up a driver license from another state, a Florida voter registration number if you are a U.S. citizen, a declaration of domicile and residency date, the address on your last IRS return, and proof of payment of utilities at the homestead address.
Exemption dollar amounts, and the later Amendment 3 path, are covered in The Homestead Exemption and Save Our Homes Cap and in Florida Amendment 3: why December 31, 2026 matters. The Amendment 3 guide already warns that homestead is not income-tax domicile.
PT-113 also says you are no longer eligible for the exemption if the residential unit is rented, if it is no longer your permanent home, or if you are no longer a permanent resident of Florida. A winter condo that is still, in fact, a second home is not made a homestead by a buyer’s preference. Only the property appraiser determines entitlement. Couples with split residency have a separate fact pattern in Buying in Brickell when only one spouse is a Florida resident.
Waldorf Astoria Residences Miami
The apartment you keep can still be a New York home
The New York Tax Department draws a hard line between domicile and residence. You may have several residences — houses, apartments, condos — and they may be in different states. You can have only one domicile. In general, that is your permanent and primary residence, the place you intend to return to or remain in after being away.
Your New York domicile does not change until you can demonstrate with clear and convincing evidence that you have abandoned it and established a new domicile outside New York. The Department’s own words matter here: it is not enough simply to file a certificate of domicile or register to vote in the new location. All aspects of a person’s life are considered.
That is why a Florida declaration, by itself, does not settle New York. Section 222.17 of the 2026 Florida Statutes lets a person who has already established a Florida domicile, but who maintains another place of abode in another state, file a sworn statement with the clerk of the circuit court that the Florida place of abode is the predominant and principal home.
The statement has to name the former residence and the other place or places of abode. It is signed under oath and recorded.
The same statute says this filing does not repeal or abrogate other methods of proving domicile. New York, for its part, says a certificate of domicile is not enough.
File the Florida declaration if your counsel wants it in the file. Do not confuse it with a New York determination.
Then comes the test that catches people who really do keep the apartment. You may be a New York State resident even if your domicile is not New York, if you maintain a permanent place of abode in New York State for substantially all of the taxable year and you spend 184 days or more in New York State during the taxable year.
In general, a permanent place of abode is a building or structure where a person can live, that you permanently maintain, and that is suitable for year-round use. It does not matter whether you own it or not. A New York City apartment that you keep available year-round is exactly the kind of place that language is written to describe.
People often call this the 183-day test; the Department’s current wording is 184 days or more. Any part of a day is a day, and you do not need to be at the apartment for the day to count, so the count is not limited to nights in your own bed. The same structure applies to New York City residency: domicile in the city, or a permanent place of abode there and 184 days or more in the city.
If you are not a resident, the Tax Department still warns that you may owe New York tax as a nonresident on income from New York sources, including income from real property located in the state. Work-from-Florida arrangements have their own rules on that same guidance; they are not a substitute for the day count.
The Ritz-Carlton Residences, South Beach
Two buildings, two bills, and a closing date that may be years out
Keeping the apartment means you will have carrying costs in both cities: the New York co-op or condo’s maintenance, assessments and property tax, and the Florida association’s estimated operating budget, insurance and property tax. Those figures are building-specific. Ask the New York building for the current charges, and ask for the current estimated operating budget and offering documents on the Florida tower. A Florida-side cost briefing already exists at What a $5 million new-development condo in South Florida really costs per year; it is not a New York budget and not a combined household number.
The lifestyle question is simpler than the tax question, and it still belongs in the documents. If you will be away for months, ask what the declaration and the rules say about vacant-unit checks, mail and packages, utilities, and how the building is staffed in the quieter season. Do not assume a brochure promise. That operational conversation is already framed in Seasonal buyer vs full-time resident and, for one West Palm Beach corridor, in Second-home ownership on West Palm Beach’s Flagler Drive.
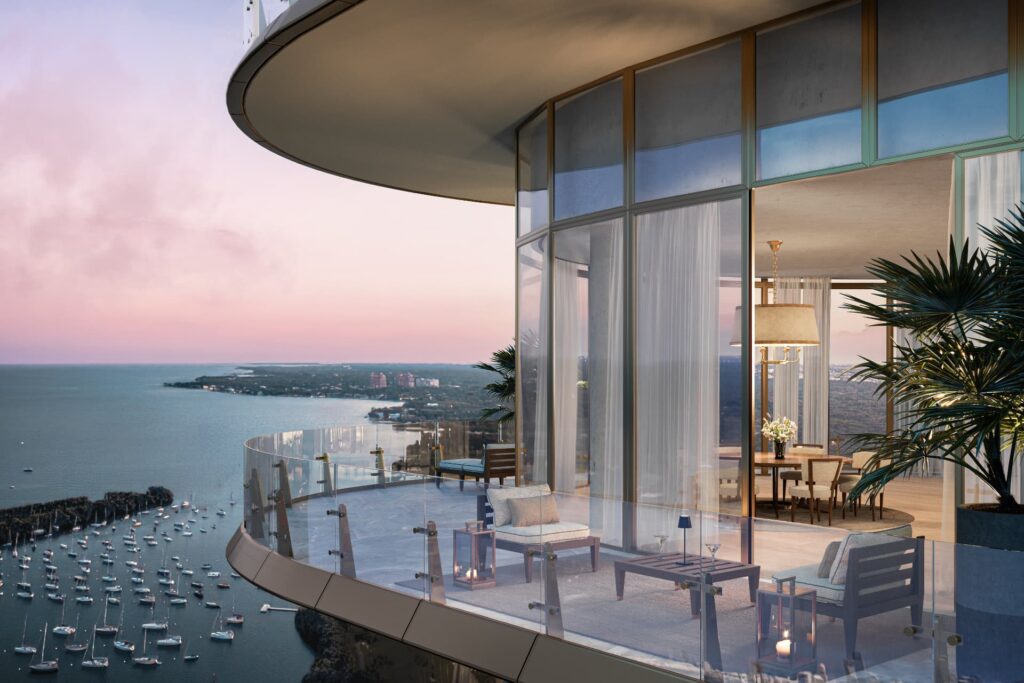
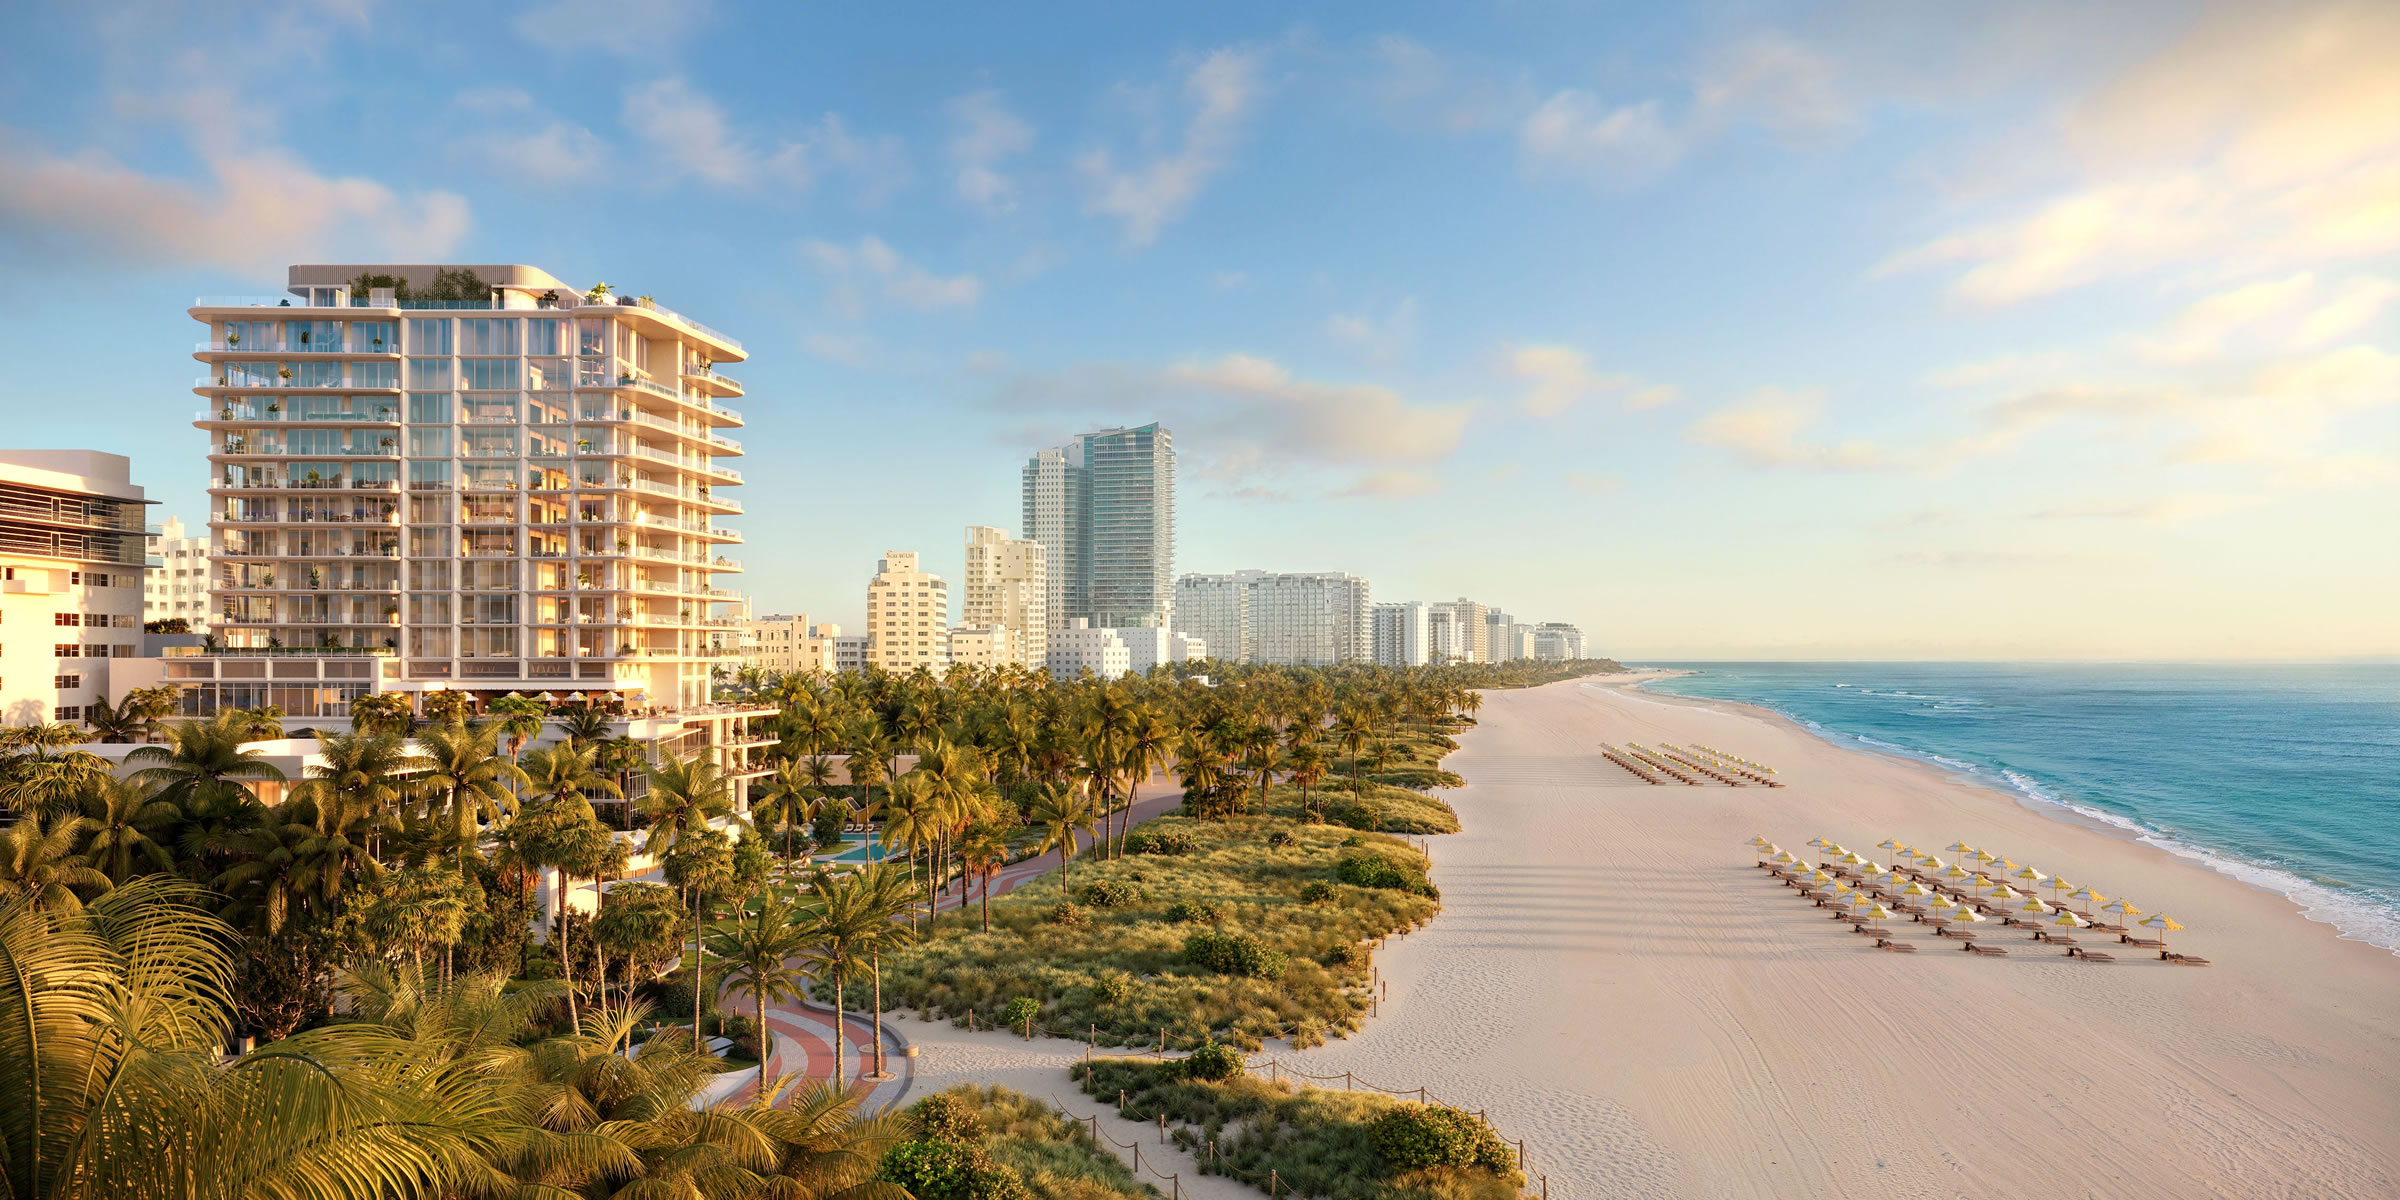
Picture towers such as Four Seasons Private Residences Coconut Grove, Waldorf Astoria Residences Miami and The Ritz-Carlton Residences, South Beach — the kind of new building you might be weighing.
The Grove terrace in the first photograph looks out over Biscayne Bay at dusk from a curved terrace and adjoining living spaces. The South Beach tower sits on the sand, looking north along Miami Beach. That is the daily scene you are buying toward, once the closing date arrives. It suits you if you want a second home in South Florida and you are not ready to give up the New York apartment.
Pre-construction adds a calendar problem that a paid reservation does not solve. PT-113 ties a given tax year’s homestead to making the property your permanent residence by January 1 of that year. A tower scheduled for 2028 cannot be that January 1 residence in an earlier year. Time the closing, the move, and any homestead filing to the year you will actually own and occupy the unit, then use How do you close on a pre-construction condo from out of state? for the mechanics of a New York closing day.
If the plan later becomes selling a Florida house you already live in, that is a different job: Sell the house you live in, or carry both until the pre-construction condo closes? Here, the New York apartment stays.
Request current pricing, remaining availability, and the offering documents before treating any published figure as a quote. Then take the tax and title questions to advisers who will put their names on the advice.
Request current price sheets, floor plans, deposit schedules and rental rules for Four Seasons Private Residences Coconut Grove, Waldorf Astoria Residences Miami, Ritz-Carlton Residences South Beach and other new towers you may be weighing.
Frequently asked questions
If I keep my New York apartment, can I still change my domicile to Florida?
Possibly, but not by owning a Florida condo alone. The New York Tax Department says you can have only one domicile, and a New York domicile does not change until you demonstrate with clear and convincing evidence that you have abandoned it and established a new one outside New York. Keeping the apartment is one of the facts that review will include. This is not legal or tax advice.
What is the 184-day test, and why do people call it 183 days?
The New York Tax Department says you may be a New York State resident, even if you are not domiciled there, if you maintain a permanent place of abode in the state for substantially all of the taxable year and spend 184 days or more in New York State. Any part of a day is a day. People often shorthand that as a 183-day test; the Department’s current wording is 184.
Does a Florida declaration of domicile settle the New York question?
No. Section 222.17 of the 2026 Florida Statutes lets you manifest and evidence a Florida domicile, including when you keep another abode in another state. The same statute says the filing does not repeal other methods of proving domicile. The New York Tax Department says it is not enough simply to file a certificate of domicile or register to vote in the new location.
Can I claim Florida homestead while I still have the New York apartment?
Only if the Florida property is your permanent residence under Florida rules, including the January 1 and March 1 tests in PT-113, and only if the county property appraiser agrees. The brochure asks whether you claim residency in another state and lists items that may be requested as proof. Homestead is not a New York income-tax determination.
When can I apply for homestead if the condo is still under construction?
PT-113 ties a tax year’s exemption to making the property your permanent residence by January 1 of that year and filing DR-501 by March 1. A pre-construction closing in a later year does not create an earlier year’s homestead. Time the filing to the year you will actually own and occupy the unit.
What does it cost to carry both homes?
It depends on the buildings. New York maintenance and Florida association charges are building-specific, so ask each building for current figures, and use the Florida-side carrying-cost guide only as a Florida briefing.
Is this legal or tax advice?
No. It is a general reading of official Florida and New York guidance, current through November 19, 2026, with related Haute Residence guides. Your contract, your returns and your advisers control the result on your facts.
Renderings courtesy of the developer.